Divorce & Real Estate
August 27, 2026
"The Mortgage Isn't My Problem Anymore" — Why That Assumption Can Be Dangerous
One of the most dangerous assumptions during divorce is: "The divorce agreement says my spouse gets the house, so the mortgage isn't my problem anymore." That may not be true, and believing it can leave you financially exposed years after the divorce is finalized.
What the CFPB Actually Says
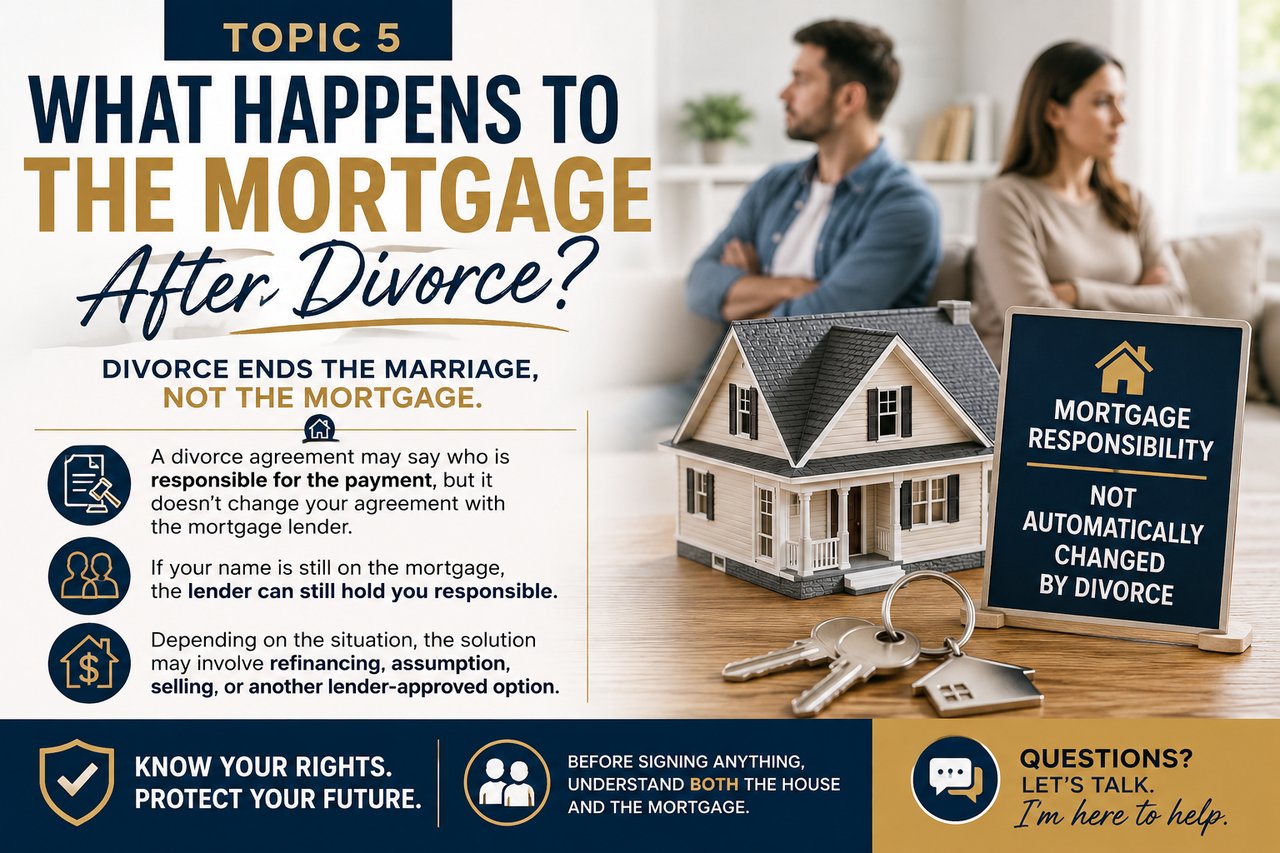
The Consumer Financial Protection Bureau explains that divorce changes the relationship between spouses but doesn't automatically change their contractual relationship with creditors. A creditor may still pursue someone who remains responsible under the loan agreement. Your settlement agreement is a contract between you and your former spouse. Your mortgage is a separate contract between you and the lender, and the lender was never a party to your divorce.
That's the entire issue in one sentence: your divorce can decide who's supposed to pay, but it can't rewrite who the bank is allowed to come after if they don't.
Three Separate Issues, Not One
This is where people get tripped up, because it feels like a single question, "who gets the house," when it's actually three separate ones:
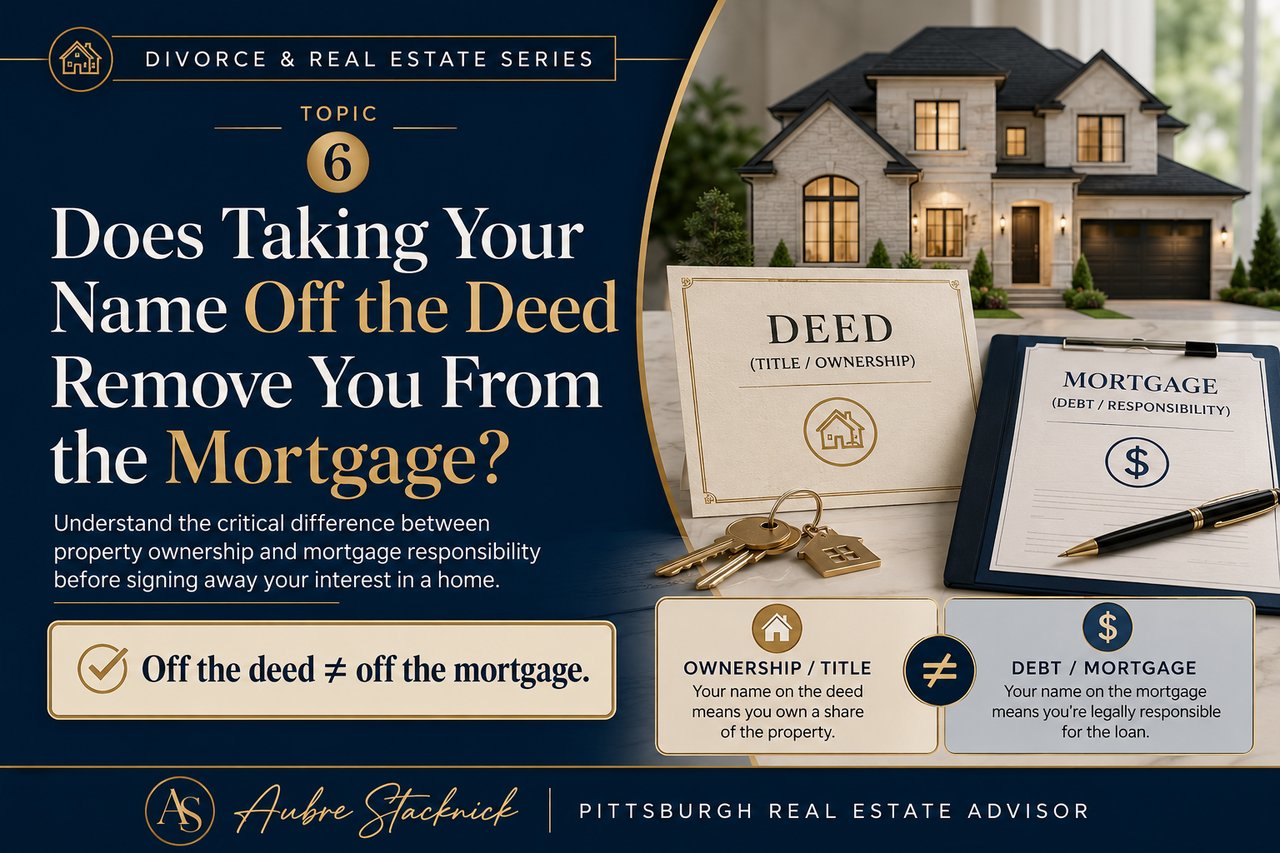
- Ownership. Who is on title? This is determined by the deed.
- Mortgage liability. Who signed the loan? This is determined by the promissory note and mortgage agreement with the lender.
- Divorce obligations. What does the settlement or court order require between the spouses? This is determined by your divorce decree or separation agreement.
These three things can all point in different directions at the same time, and often do. It's entirely possible to be off the deed, still on the mortgage, and technically "not responsible" per the divorce decree, all at once. Only one of those three actually determines whether a lender can come after you.
Your Real Options
Depending on the situation, options may include:
- Selling the property, which pays off the loan and ends both spouses' liability at closing.
- Refinancing, where the spouse keeping the home takes out a new loan solely in their name and pays off the old joint mortgage.
- An approved assumption, where the remaining spouse takes over the existing loan and the lender formally releases the other spouse from liability.
The CFPB Has Specifically Addressed Mortgage Assumptions After Divorce
This is the part that surprises a lot of people, because assumption is often overlooked in favor of refinancing. The CFPB has specifically addressed mortgage assumptions following divorce and notes that a successor homeowner may be able to assume responsibility for the mortgage, subject to applicable underwriting requirements.
Under CFPB mortgage servicing rules, someone who receives an ownership interest in a home as a result of a divorce or legal separation generally qualifies as a "successor in interest." Once a servicer confirms that status, the successor has the right to get information about the loan, continue making payments, and be evaluated for loss mitigation options like a loan modification, without necessarily having to refinance. If that spouse wants to formally take over the loan and remove the other spouse's name from it, they generally need to assume the mortgage, which typically requires passing the lender or investor's underwriting criteria, meaning income, credit, and debt-to-income requirements similar to a standard loan application.
The CFPB has also found, through its own research, that homeowners in this exact situation are sometimes incorrectly told by servicers that they have no choice but to refinance at current interest rates, even when federal mortgage program guidelines would allow an assumption instead. If a lender pushes back on this option, it's worth asking directly whether an assumption is available before assuming refinancing is the only path.
Why This Matters More Than It Seems
Assumption isn't right for every situation, but for a spouse keeping a home with a mortgage locked in at a lower interest rate than what's currently available, it can be significantly more valuable than a full refinance. Refinancing means giving up the old rate entirely. An approved assumption can let the remaining spouse keep it, while still formally releasing the departing spouse from the debt.
Before You Transfer Ownership, Understand Both Sides
Before transferring ownership of a property during divorce, make sure you understand both the deed and the debt. Signing a quitclaim deed resolves the ownership question. It does nothing on its own to resolve the mortgage question. Treating a settlement agreement as the end of the conversation with the lender, rather than the start of one, is exactly how people end up on the hook for a house they no longer own.
Practical Steps Before You Sign Anything
- Get written confirmation from the lender about whether an assumption is available on your specific loan before assuming refinancing is the only path.
- If you're the departing spouse, notify the servicer of the divorce and your status as a former co-borrower or successor in interest, and get everything about liability in writing.
- Don't rely on the divorce decree alone to protect your credit. Follow up with the lender directly to confirm the mortgage itself has actually been resolved.
- If a servicer tells you refinancing is your only option, ask specifically about assumption eligibility under the applicable federal mortgage program guidelines before accepting that answer.
The Bottom Line
A divorce settlement can decide who's supposed to pay the mortgage. It can't decide who the lender is legally allowed to pursue if that payment doesn't happen. Ownership, mortgage liability, and divorce obligations are three separate questions with three separate answers, and confusing them is one of the most common, and most costly, mistakes in divorce real estate. Confirm the mortgage resolution directly with your lender, explore assumption as well as refinancing, and don't consider this settled until the bank says it is.
FAQ: Mortgage Liability After Divorce
If my divorce decree says my spouse is responsible for the mortgage, am I still liable? Potentially, yes. A divorce decree is an agreement between spouses, but it doesn't change your contractual relationship with the mortgage lender. If your name is still on the loan, the lender can generally still pursue you if payments aren't made, regardless of what the decree says.
What is a "successor in interest" under CFPB rules? A successor in interest is someone who receives an ownership interest in a mortgaged property through specific circumstances, including a divorce or legal separation. Once a servicer confirms that status, the successor generally has the right to get loan information, make payments, and be evaluated for loss mitigation options.
Can I assume my spouse's mortgage instead of refinancing after divorce? In many cases, yes. The CFPB has noted that a successor homeowner may be able to assume responsibility for the mortgage, subject to the lender or investor's underwriting requirements. This can be valuable when the existing loan has a lower interest rate than what's currently available.
Does removing my name from the deed also remove me from the mortgage? No. Ownership and mortgage liability are determined by two separate documents. Removing your name from the deed doesn't affect the mortgage, and removing your name from the mortgage doesn't affect ownership. Each requires its own separate resolution.
What should I do before transferring ownership of the house in my divorce? Confirm directly with the lender how the mortgage itself will be resolved, whether through sale, refinance, or an approved assumption, before or alongside the ownership transfer. Don't treat a signed deed or a divorce decree as proof that your mortgage liability has ended.
Related Reading
Best Selling Options in a Divorce (free guide)
Can You Buy Another House Before Your Divorce Is Final?
How Do You Determine What a House Is Worth During Divorce?
What Happens When One Spouse Wants to Sell the House and the Other Doesn't?
Does Taking Your Name Off the Deed Remove You From the Mortgage?
Should You Sell the House Before or After the Divorce Is Final?
Sources
- Consumer Financial Protection Bureau, "Issue Spotlight: Homeowners face problems with mortgage companies after divorce or death of a loved one" — https://www.consumerfinance.gov/data-research/research-reports/homeowners-face-problems-with-mortgage-companies-after-divorce-or-death-of-a-loved-one/
- Consumer Financial Protection Bureau, "CFPB Report Finds Mortgage Companies Create Obstacles for Homeowners After Death or Divorce" — https://www.consumerfinance.gov/about-us/newsroom/cfpb-report-finds-mortgage-companies-create-obstacles-for-homeowners-after-death-or-divorce/
- Consumer Financial Protection Bureau, § 1024.31 Definitions (successor in interest) — https://www.consumerfinance.gov/rules-policy/regulations/1024/31/
- Consumer Financial Protection Bureau, § 1024.38 General servicing policies, procedures, and requirements — https://www.consumerfinance.gov/rules-policy/regulations/1024/38/
About the Author
Aubre Stacknick is a Global Real Estate Advisor with Piatt Sotheby's International Realty, serving Pittsburgh and the surrounding area. With 20+ years across construction, custom home building, and real estate, and having navigated divorce herself, she brings a practical, firsthand understanding of both the financial and emotional sides of buying, selling, or holding property through a divorce.
📞 412-721-3496 📧 [email protected] 🌐 www.aubrestacknick.com
Curious what your home is worth in today's market? Get a free home valuation and find out where you stand.
mortgage liability after divorce, CFPB successor in interest, mortgage assumption divorce, divorce decree mortgage responsibility, deed vs mortgage divorce, divorce real estate Pittsburgh
This blog is for general informational purposes only and is not legal or financial advice. Confirm your specific situation with your lender and attorney.