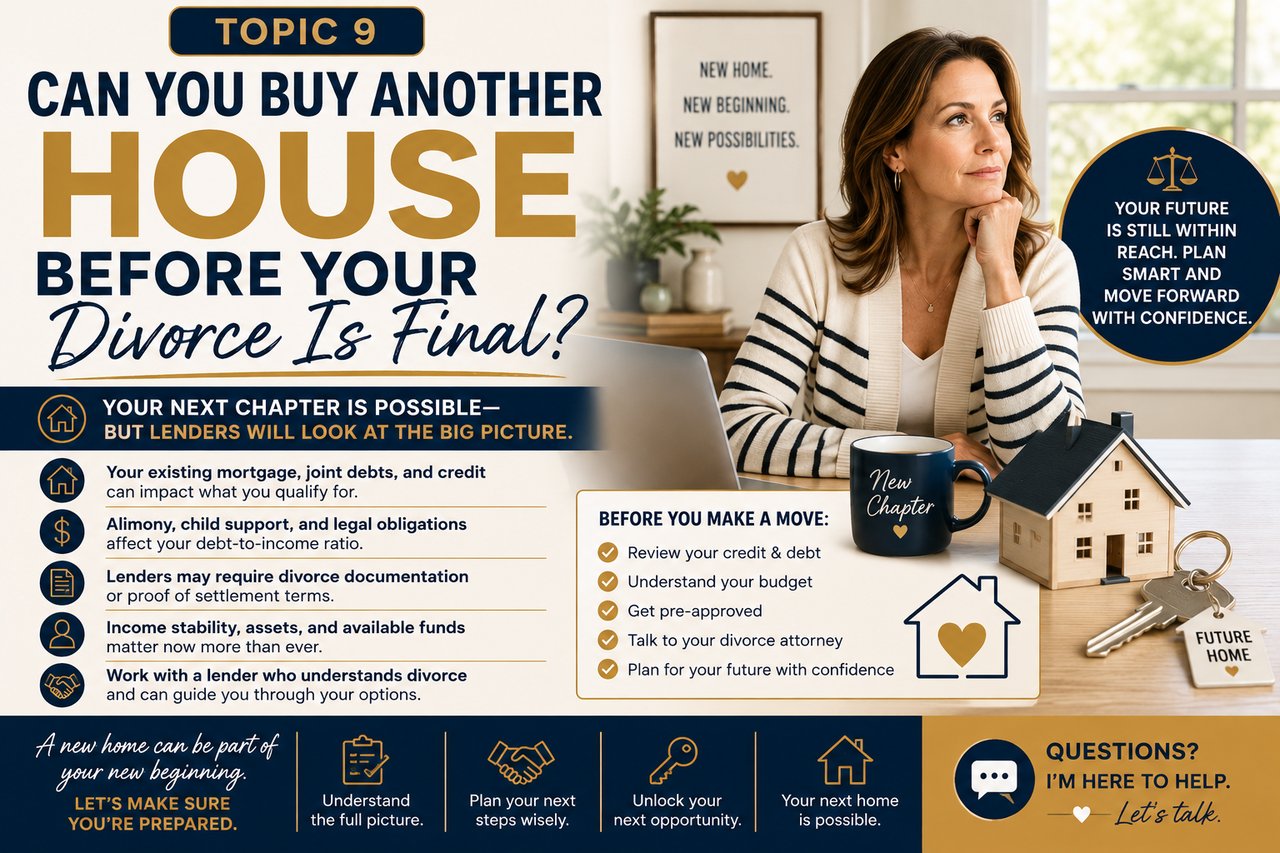
Can You Buy Another House Before Your Divorce Is Final?
Quick answer: In most states, yes, you can legally buy a house before your divorce is finalized. But being legally permitted to purchase property and being able to qualify for the mortgage you want are two separate issues, and conflating them is where most people run into trouble. The real obstacle usually isn't the law. It's the math: your income, your existing marital mortgage, your support obligations, and how a lender is required to treat all of it.
This guide walks through exactly how that math works, loan type by loan type, so you know what to expect before you fall for a house you can't actually get financed.
What a Lender Actually Looks At
A lender doesn't care what your divorce decree says you're "entitled" to. It cares whether you can realistically make the payment, on this loan, on top of everything else you're carrying. That means underwriting will look at:
- Income.
- Credit.
- Current liabilities.
- Joint debt.
- The existing marital-home mortgage.
- Alimony or child-support obligations, when applicable.
- Available assets.
- Relevant separation or divorce documentation.
Most of these are self-explanatory. The one that trips people up almost every time is the mortgage on the house they're leaving behind.
The Existing Mortgage Doesn't Disappear Because You Moved Out
If your name remains on the mortgage, don't assume a lender will ignore that debt just because your spouse plans to keep the house. On paper, you're still legally obligated to that loan until it's refinanced, assumed, or paid off, and underwriting treats it that way unless you can document otherwise.
This is a documentation problem, not a hypothetical one, and the rules differ depending on the type of loan you're trying to get.
How Fannie Mae Treats the Old Mortgage
Under Fannie Mae's Selling Guide, when a debt has been assigned to your spouse by court order, such as a divorce decree, and the lender confirms that assignment with documentation, the lender is not required to count that mortgage as part of your monthly obligations. Fannie Mae's guidance goes further for real estate specifically: when your interest in the marital home has been bought out by your spouse but the lender hasn't formally released you from the loan, the resulting contingent liability doesn't have to be counted once the lender has documentation confirming the title transfer. Notably, Fannie Mae does not require proof of a specific payment history for this exclusion, just documentation of the legal assignment and, where relevant, the title transfer.
How FHA Treats the Old Mortgage
FHA loans are stricter. Under HUD's underwriting requirements, a contingent liability like an old marital mortgage generally must be included in your debt-to-income ratio unless you can document that the responsible party, meaning your spouse, has made 12 consecutive months of on-time payments after the divorce decree or separation agreement took effect. The lender will typically want a copy of the decree assigning responsibility for the mortgage, plus evidence of that payment history, such as bank statements or a mortgage payment history report.
In practice, this means a departing spouse pursuing an FHA loan may need to wait roughly a year after the settlement before that old mortgage stops counting against them, unless the loan is refinanced or the home is sold first.
What This Means for You
The American Bar Association's 2026 discussion of divorce mortgages makes the same point from the legal side: an existing marital mortgage can affect a departing spouse's debt-to-income analysis, and documentation regarding the former spouse's responsibility and payment history is what determines whether that mortgage gets excluded. Read the ABA's full analysis for family law practitioners if you want the legal side in more depth.
The practical takeaway: know which loan type you're pursuing early, because it directly changes how long you may need to wait, or what documentation you need to gather, before that old mortgage stops working against you.
Alimony and Child Support: A Debt and a Potential Asset
Support obligations cut both ways in underwriting:
- If you pay it: Court-ordered alimony or child support is typically counted as a monthly liability, the same as a car payment or credit card minimum, and it reduces how much mortgage you can qualify for.
- If you receive it: It can sometimes be counted as qualifying income, but lenders generally require documentation, such as the divorce decree or separation agreement, along with evidence you've actually been receiving the payments consistently, often for the prior 12 months, and that the payments are likely to continue for several years.
If your support arrangement is brand new, don't assume it will immediately boost your buying power. Lenders want a track record, not just a court order.
Documentation Checklist Before You Talk to a Lender
Having these ready speeds up the conversation and gives you a far more accurate picture of what you can actually qualify for:
- Final divorce decree or separation agreement, if one exists, specifying who is responsible for the existing mortgage.
- Recent pay stubs and two years of tax returns.
- Statements showing joint debts and which spouse is paying them.
- Mortgage statements for the marital home, including current balance and payment history.
- Documentation of alimony or child support, paid or received, and proof of a consistent payment history if applicable.
- Bank and asset statements for your down payment and reserves.
The Order That Actually Works
Given everything above, the sequence matters more than most people expect:
Lender conversation → realistic budget → home search.
Not the reverse. Falling in love with a house first and discovering the financing problem second is one of the most common, and most avoidable, ways this process goes sideways. A lender conversation early on tells you what you can actually qualify for given your current DTI, your support obligations, and the status of the marital mortgage, before you've gotten emotionally attached to a listing that was never realistic to begin with.
A Few Other Things Worth Knowing
- State property law matters. In community property states, an asset purchased while you're still legally married can sometimes be treated as marital property regardless of whose name is on the title. Coordinate timing with your family law attorney before you sign a purchase contract.
- Loan type shapes your timeline. As shown above, conventional loans through Fannie Mae can sometimes offer more flexibility than FHA on how quickly the old mortgage stops counting against you.
- A written settlement helps more than a verbal understanding. Lenders work off documentation, not intentions. A signed agreement specifying who is responsible for the marital mortgage carries far more weight than an informal arrangement between spouses.
The Bottom Line
Buying before your divorce is final isn't off the table. But it depends on documentation, timing, loan type, and how the existing home is being handled, not just on whether your attorney says you're free to buy. Talk to a lender first, get clear on how your specific loan type treats the old mortgage, and build your budget around real numbers. Everything else, the search, the offer, the closing, gets a lot easier once you know what you're actually working with.
Frequently Asked Questions
Can I legally buy a house while my divorce is still pending?
In most states, yes, you can legally purchase property before a divorce is finalized. Whether you can qualify for the mortgage you want is a separate question that depends on your income, credit, existing debts, and how the marital mortgage is being handled.
Will my current mortgage count against me if my spouse is keeping the house?
It can. If your name is still on the existing mortgage, that payment typically counts in your debt-to-income ratio unless documentation shows the debt was legally assigned to your spouse and, for many loan types, that they have a consistent payment history.
How is a divorced spouse's old mortgage treated differently by Fannie Mae versus FHA?
Fannie Mae generally excludes the old mortgage from your debt-to-income ratio once the lender has documentation confirming the debt was assigned to your spouse by court order, without requiring a specific payment history. FHA loans generally require documented proof of 12 months of on-time payments by the responsible spouse before excluding the debt.
Does alimony or child support affect what I can qualify for?
It can work both ways. Alimony or child support you owe is typically counted as a liability. Alimony or child support you receive can sometimes be counted as qualifying income, with documentation and a consistent receipt history, often around 12 months.
Should I talk to a lender before I start house hunting during a divorce?
Yes. Getting a clear picture of what you can actually qualify for, given your income, support obligations, and existing mortgage status, before you start looking prevents the common problem of falling for a house you can't get financed.
What documents does a lender need to exclude my old mortgage from my debt-to-income ratio?
Typically the final divorce decree or separation agreement showing who is responsible for the mortgage, and depending on the loan type, evidence such as canceled checks, bank statements, or a payment history report showing the responsible spouse has been making the payments.
Can my spouse have an interest in the new home I buy while still married?
In some states, property acquired while still legally married can be considered marital property regardless of whose name is on the title, which is why coordinating the timing and structure of a new purchase with a family law attorney matters before signing a contract.
Related Reading
Best Selling Options in a Divorce (free guide)
How Do You Determine What a House Is Worth During Divorce?
What Happens When One Spouse Wants to Sell the House and the Other Doesn't?
Does Taking Your Name Off the Deed Remove You From the Mortgage?
Should You Sell the House Before or After the Divorce Is Final?
Sources
- American Bar Association — What Divorce Lawyers Need to Know About Mortgages and Refinancing (2026)
- Fannie Mae Selling Guide — Monthly Debt Obligations, B3-6-05
- Fannie Mae Selling Guide — Qualifying Impact of Other Real Estate Owned, B3-6-06
- FHA.com — FHA Loans and Your Existing Debts
- FHA.com — Verifying Alimony and/or Child Support for FHA Loans
About the Author
Aubre Stacknick is a Global Real Estate Advisor with Piatt Sotheby's International Realty, serving Pittsburgh and the surrounding area. With 20+ years across construction, custom home building, and real estate, and having navigated divorce herself, she brings a practical, firsthand understanding of both the financial and emotional sides of buying, selling, or holding property through a divorce.
📞 412-721-3496
📧 [email protected]
🌐 www.aubrestacknick.com
Curious what your home is worth in today's market? Get a free home valuation and find out where you stand.
buying a house during divorce, divorce mortgage qualification, debt-to-income divorce, contingent liability mortgage, FHA divorce mortgage rules, Fannie Mae divorce mortgage, new home purchase divorce, divorce real estate Pitts