Can I Keep the House After Divorce? What "Affordability" Actually Means
Potentially, but getting the house and being able to afford the house are different things. This is one of the most emotionally loaded decisions in a divorce, and it's exactly the kind of decision where emotion and math need to be separated before anything gets signed.
Start With Market Value and Equity
A homeowner considering keeping the marital residence should start with market value and equity, not with how attached they feel to the house. Suppose a home is worth $600,000 and has substantial equity. That equity isn't automatically yours to keep just because you're the one staying in the house.
Keeping it may require addressing the other spouse's interest as part of the overall property settlement, whether through a cash buyout, an offset against other assets, or another arrangement negotiated as part of the divorce. In Pennsylvania, that settlement is governed by equitable distribution under 23 Pa.C.S. § 3502, meaning the split isn't automatically 50/50, it depends on the specific circumstances of the marriage. Either way, the other spouse's share has to be resolved somehow before "keeping the house" is actually final.
Then There's the Mortgage
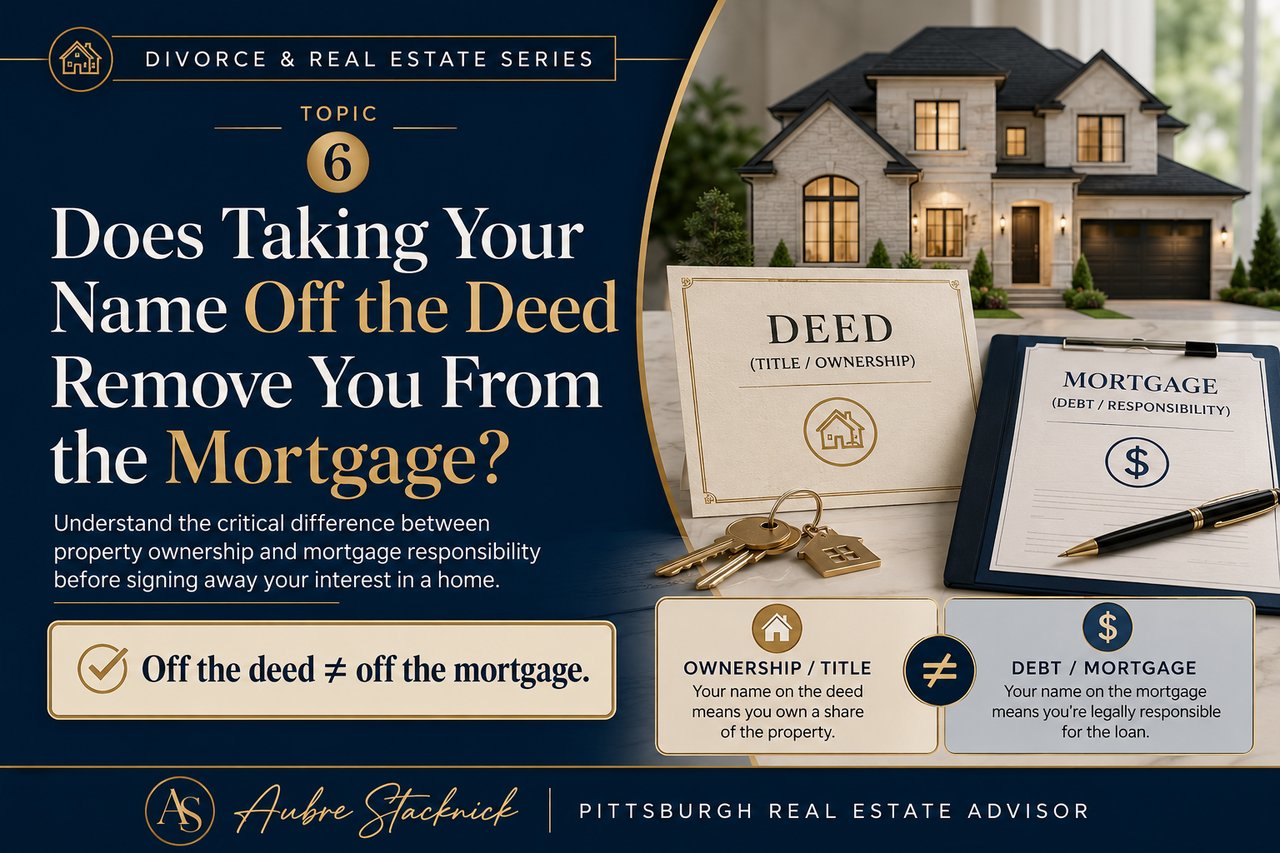
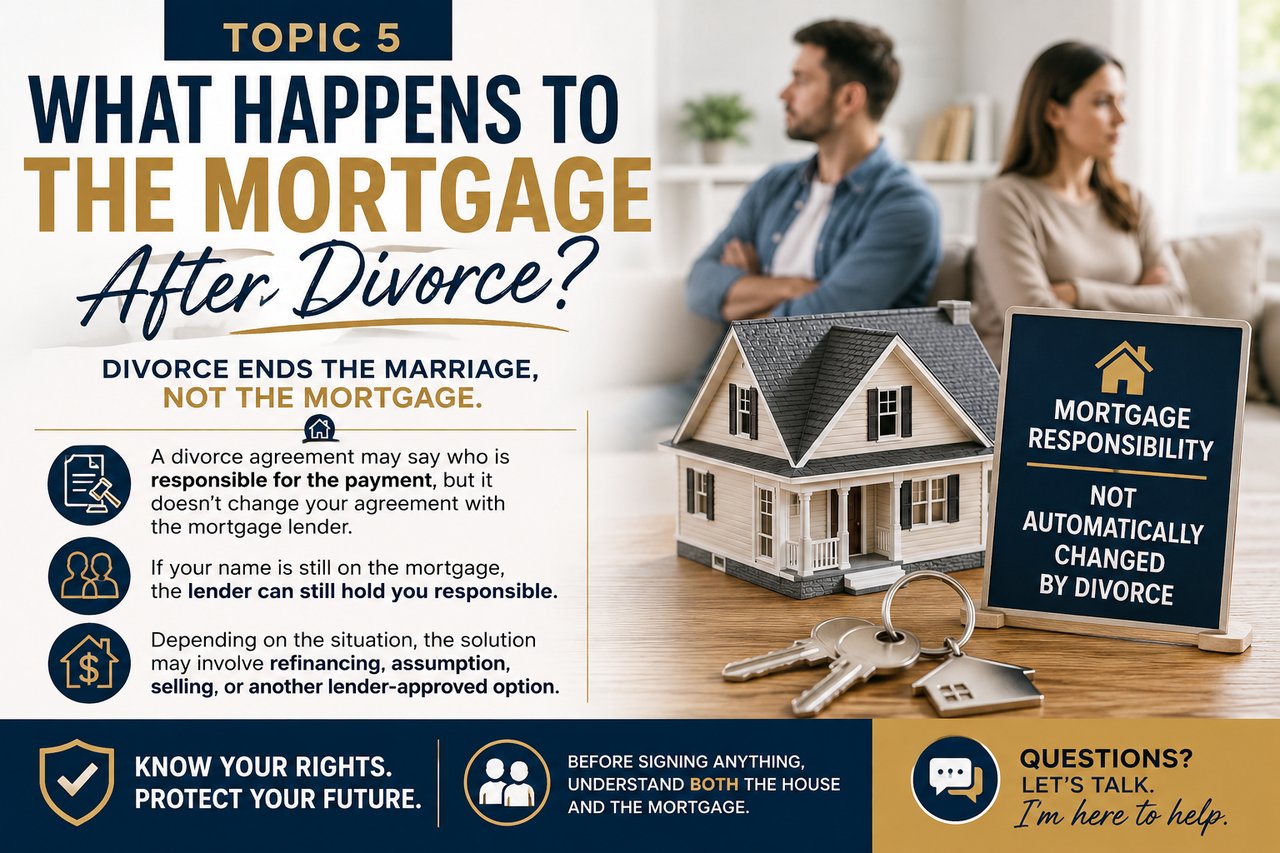
If both spouses are borrowers, transferring ownership alone does not automatically eliminate one person's responsibility for the loan. This is separate from the equity question entirely. A deed transfer resolves who owns the house. It does nothing on its own to resolve who the bank can still come after if a payment is missed.
Depending on the mortgage, refinancing or a qualifying assumption may be considered. This is worth understanding in detail, because a lot of people assume refinancing is the only option. The CFPB notes that some successor homeowners after divorce can seek an assumption and release of the original borrower, subject to applicable underwriting requirements. Under CFPB rules, a spouse who receives the property through a divorce generally qualifies as a "successor in interest," which gives them specific rights, including the ability to pursue an assumption of the existing loan rather than being forced into a full refinance, provided they can meet the lender's underwriting standards. That distinction matters most when the existing mortgage has a significantly lower rate than what's currently available, since assumption can preserve that rate while a refinance would give it up entirely.
Now Calculate the Real Cost of Ownership
This is the step people skip, and it's the one that matters most. Keeping the house isn't just about the mortgage payment. The full cost of ownership includes:
- Mortgage principal and interest.
- Property taxes.
- Insurance.
- HOA fees, if applicable.
- Utilities.
- Routine maintenance.
- Major repairs.
That last one is easy to underestimate. Industry data commonly puts routine annual home maintenance at roughly 1% to 4% of a home's value, depending on the home's age, size, and condition, with national averages for actual maintenance spending running in the range of several thousand dollars a year even before a major repair like a roof or HVAC replacement comes up. On a $600,000 home, that's a maintenance range that alone can run from several thousand to well over ten thousand dollars in a given year, on top of the mortgage, taxes, and insurance.
Two Incomes vs. One
A home that comfortably operated with two incomes may become financially restrictive with one. This is the part that's easy to overlook in the middle of a divorce, when staying in the family home can feel like the priority that matters most, especially with kids involved. But a household budget that worked when two paychecks were covering the mortgage, taxes, insurance, maintenance, and everything else doesn't automatically shrink its expenses just because it now runs on one income. The house doesn't get cheaper. The income covering it does.
The Question That Actually Matters
The right question isn't simply: "Can I keep my house?" It's: "What does keeping this property mean for the rest of my financial life?"
That reframing matters because the first question has an emotional pull toward "yes." The second question forces an honest look at retirement savings, emergency funds, the kids' future expenses, and whether the house is quietly consuming resources that should be going elsewhere.
A Practical Way to Answer It
- Get a current market valuation so you know the real equity number, not an outdated guess.
- Work with your attorney to understand how the other spouse's share will be resolved under your state's property division law.
- Talk to a lender early about whether refinancing or an assumption is realistic for your income and credit on your own, not as part of a two-income household.
- Add up the full cost of ownership, not just the mortgage, including a realistic maintenance reserve, not just what the current bills happen to be today.
- Run the numbers against your full post-divorce budget, including retirement contributions, childcare, and an emergency fund, not just whether the mortgage payment technically fits.
- If the numbers are tight, have an honest conversation about whether keeping the house serves your long-term finances, or whether it's serving an emotional attachment to the past.
The Bottom Line
Keeping the marital home after divorce is often possible, but "possible" and "financially sound" aren't the same thing. Between resolving the other spouse's equity interest, addressing the existing mortgage liability, and covering the full real cost of ownership on a single income, there's a lot more to the decision than whether your name ends up on the deed. Answer the bigger question, what keeping this house means for the rest of your financial life, before you answer the smaller one.
FAQ: Keeping the House After Divorce
Can I automatically keep the house if I want it in a divorce? Not automatically. Keeping the house generally requires resolving the other spouse's equity interest as part of the property settlement, and in Pennsylvania that's governed by equitable distribution rather than a set formula. It also requires addressing the mortgage, since ownership and loan liability are separate issues.
Does transferring the house into my name remove my ex from the mortgage? No. If both spouses are borrowers on the original loan, a deed transfer alone doesn't remove either party from mortgage liability. That typically requires refinancing, a lender-approved assumption, or paying off the loan.
Can I assume my spouse's mortgage instead of refinancing after divorce? In some cases, yes. The CFPB notes that a successor homeowner after divorce may be able to pursue an assumption and release of the original borrower, subject to the lender's underwriting requirements. This can be valuable if the existing mortgage rate is lower than current market rates.
How much should I budget for home maintenance if I keep the house? A commonly cited guideline is roughly 1% to 4% of the home's value per year, depending on its age, size, and condition, in addition to the mortgage, property taxes, insurance, and utilities. Older or larger homes generally fall toward the higher end of that range.
How do I know if I can actually afford to keep the house on one income? Add up the full cost of ownership, mortgage, taxes, insurance, HOA fees if applicable, utilities, and a realistic maintenance reserve, and compare it against your full single-income budget, including savings and other financial priorities, not just whether the mortgage payment alone fits.
Related Reading
Best Selling Options in a Divorce (free guide)
Can You Buy Another House Before Your Divorce Is Final?
How Do You Determine What a House Is Worth During Divorce?
What Happens When One Spouse Wants to Sell the House and the Other Doesn't?
Does Taking Your Name Off the Deed Remove You From the Mortgage?
Should You Sell the House Before or After the Divorce Is Final?
What Happens to the Mortgage After Divorce?
Does Pennsylvania Split the House 50/50 in a Divorce?
How Does Buying Your Spouse Out of the House Work?
Sources
- Consumer Financial Protection Bureau, § 1024.31 Definitions (successor in interest) — https://www.consumerfinance.gov/rules-policy/regulations/1024/31/
- Consumer Financial Protection Bureau, "Issue Spotlight: Homeowners face problems with mortgage companies after divorce or death of a loved one" — https://www.consumerfinance.gov/data-research/research-reports/homeowners-face-problems-with-mortgage-companies-after-divorce-or-death-of-a-loved-one/
- 23 Pa.C.S. § 3502, Equitable Division of Marital Property — https://www.legis.state.pa.us/WU01/LI/LI/CT/HTM/23/00.035.002.000..HTM
- State Farm, "How Much To Budget for Home Maintenance" — https://www.statefarm.com/simple-insights/residence/how-to-budget-and-save-for-home-maintenance
About the Author
Aubre Stacknick is a Global Real Estate Advisor with Piatt Sotheby's International Realty, serving Pittsburgh and the surrounding area. With 20+ years across construction, custom home building, and real estate, and having navigated divorce herself, she brings a practical, firsthand understanding of both the financial and emotional sides of buying, selling, or holding property through a divorce.
📞 412-721-3496 📧 [email protected] 🌐 www.aubrestacknick.com
Curious what your home is worth in today's market? Get a free home valuation and find out where you stand.
can I keep the house after divorce, affording the house after divorce, divorce mortgage assumption, cost of homeownership divorce, single income mortgage divorce, divorce real estate Pittsburgh
This blog is for general informational purposes only and is not legal, financial, or tax advice. Confirm your specific situation with your attorney, lender, and financial advisor.