How Does a Divorce Home Buyout Actually Work?
A buyout generally means one spouse retains the property while the other transfers their ownership interest under the divorce settlement. It sounds simple in a sentence. In practice, it involves a value question, a legal question, a funding question, and a mortgage question, and all four need answers before it actually works.
Step One: Establish the Value
The starting point is often value. Assume a property has a market value of $600,000 and a $300,000 mortgage. That suggests approximately $300,000 of gross equity before considering other relevant obligations or negotiated adjustments, things like closing costs, agent commissions, liens, or capital gains exposure if the home were sold instead.
That $300,000 is the number everything else gets built on, which is exactly why it needs to come from a real, current market analysis rather than an app estimate or a number either spouse remembers from a few years ago.
Step Two: Understand That Equity Isn't Automatically Split in Half
But that does not automatically mean one spouse receives $150,000. This is the part people consistently get wrong.
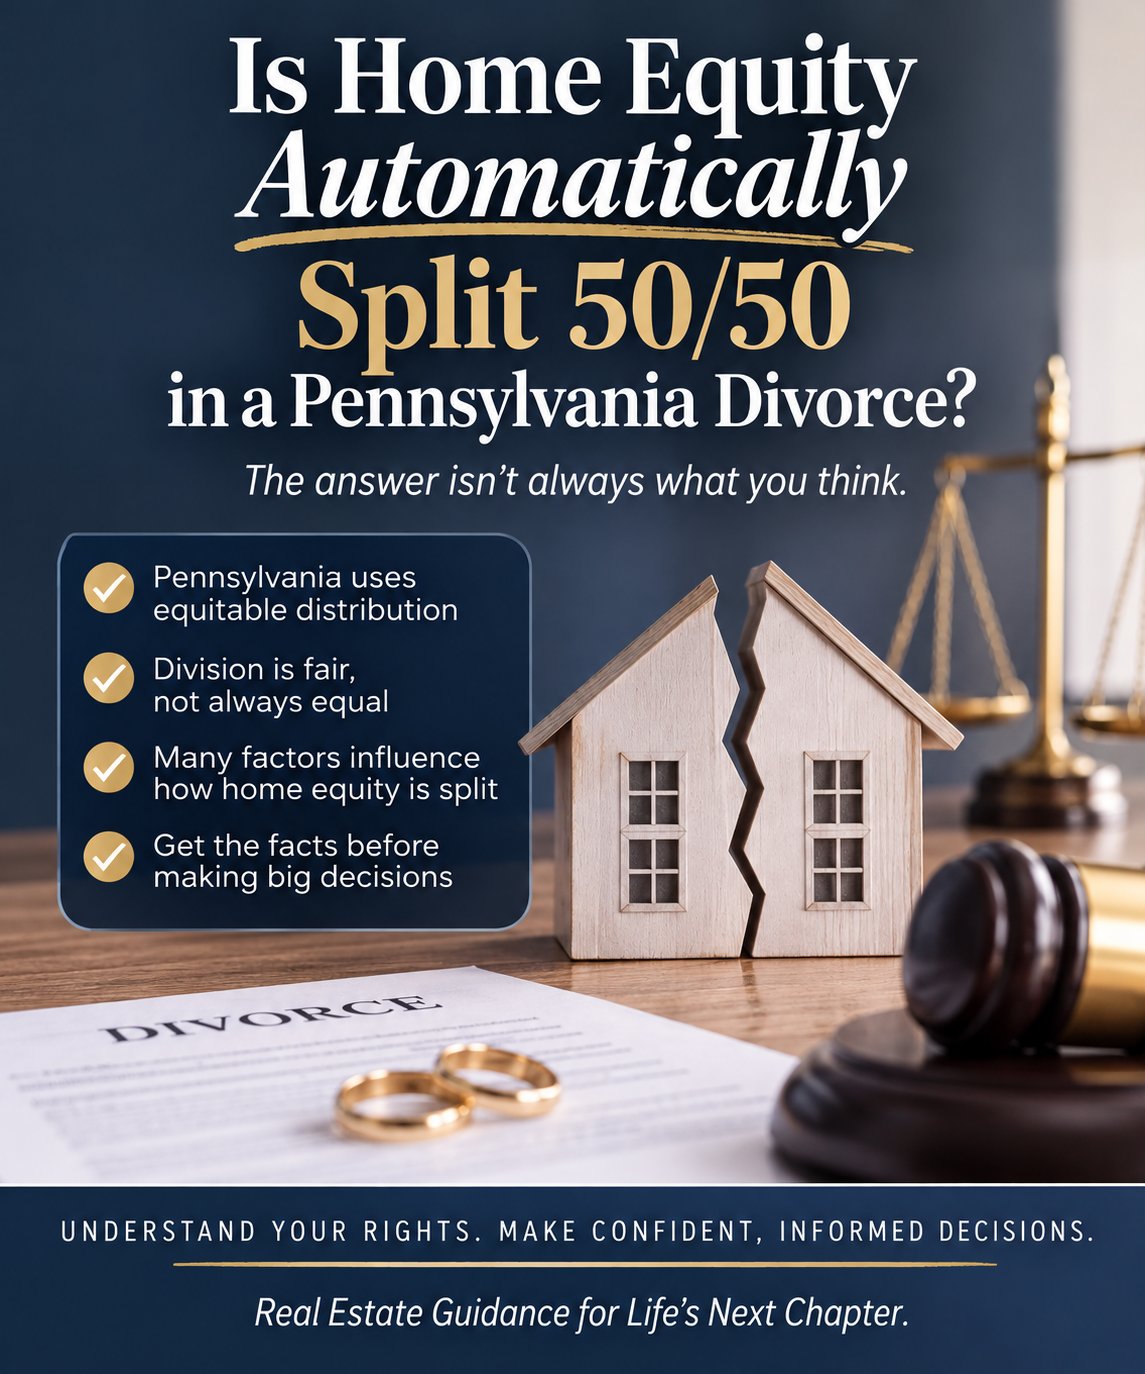
Pennsylvania uses equitable distribution. The overall division of marital property depends on the circumstances and applicable legal process rather than an automatic 50/50 formula. Under 23 Pa.C.S. § 3502, a court weighs factors like the length of the marriage, each spouse's income and earning capacity, contributions to the marriage, and tax consequences, among others, when deciding what's fair. The $300,000 gross equity figure is the pie. How it gets sliced is a legal determination, not a math problem.
Step Three: Figure Out Where the Buyout Money Comes From
Once a buyout amount is determined, another question arises: where does the money come from? Possibilities can include:
- Available cash. Savings or liquid assets used to pay the departing spouse directly.
- Other assets. Offsetting the house equity against retirement accounts, investment accounts, or other property, so the departing spouse receives value elsewhere instead of cash from the house itself.
- Refinancing proceeds. The spouse keeping the home takes out a new loan, larger than the existing mortgage, and uses the difference to pay the departing spouse.
- Other arrangements structured through the divorce settlement, such as a payment plan, a note secured against the property, or a delayed buyout tied to a future sale or refinance date.
How a Refinance Buyout Actually Works
Since refinancing is the most common funding method, it's worth walking through the mechanics. If a home is worth $600,000 with a $300,000 mortgage and the settlement calls for a $150,000 buyout, the spouse keeping the home would generally need to refinance for roughly $450,000: enough to pay off the original $300,000 loan and provide the $150,000 buyout at closing.
Two things matter here. First, most standard cash-out refinances are capped around 80% loan-to-value, which can limit how much a spouse can actually borrow against the home, depending on the numbers involved. Second, some states recognize specific legal mechanisms, sometimes called owelty liens or similar terms, that can allow more favorable refinance treatment specifically for divorce buyouts. Whether something like that applies in your situation is a question for your attorney and lender together, since it varies significantly by state and by how the settlement agreement is worded.
Step Four: Don't Ignore the Existing Mortgage
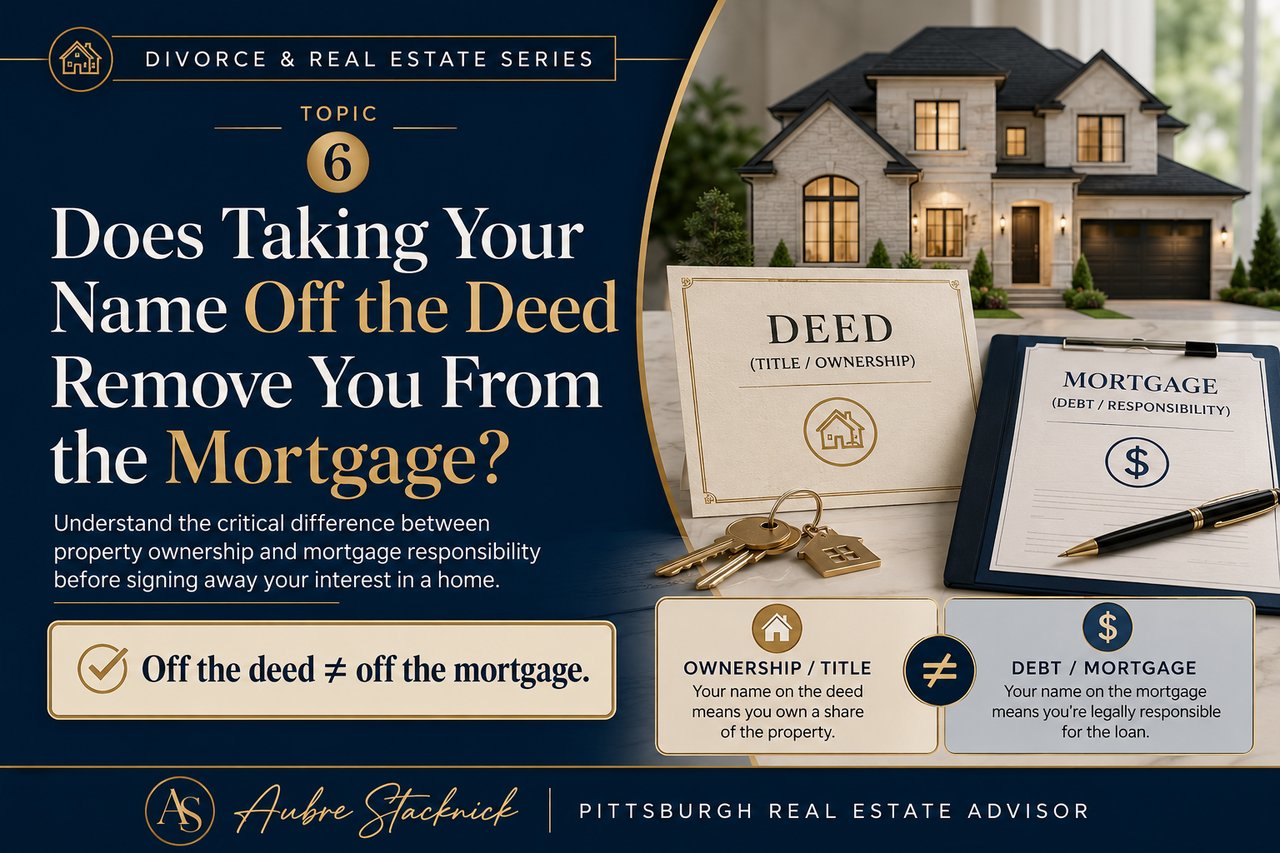
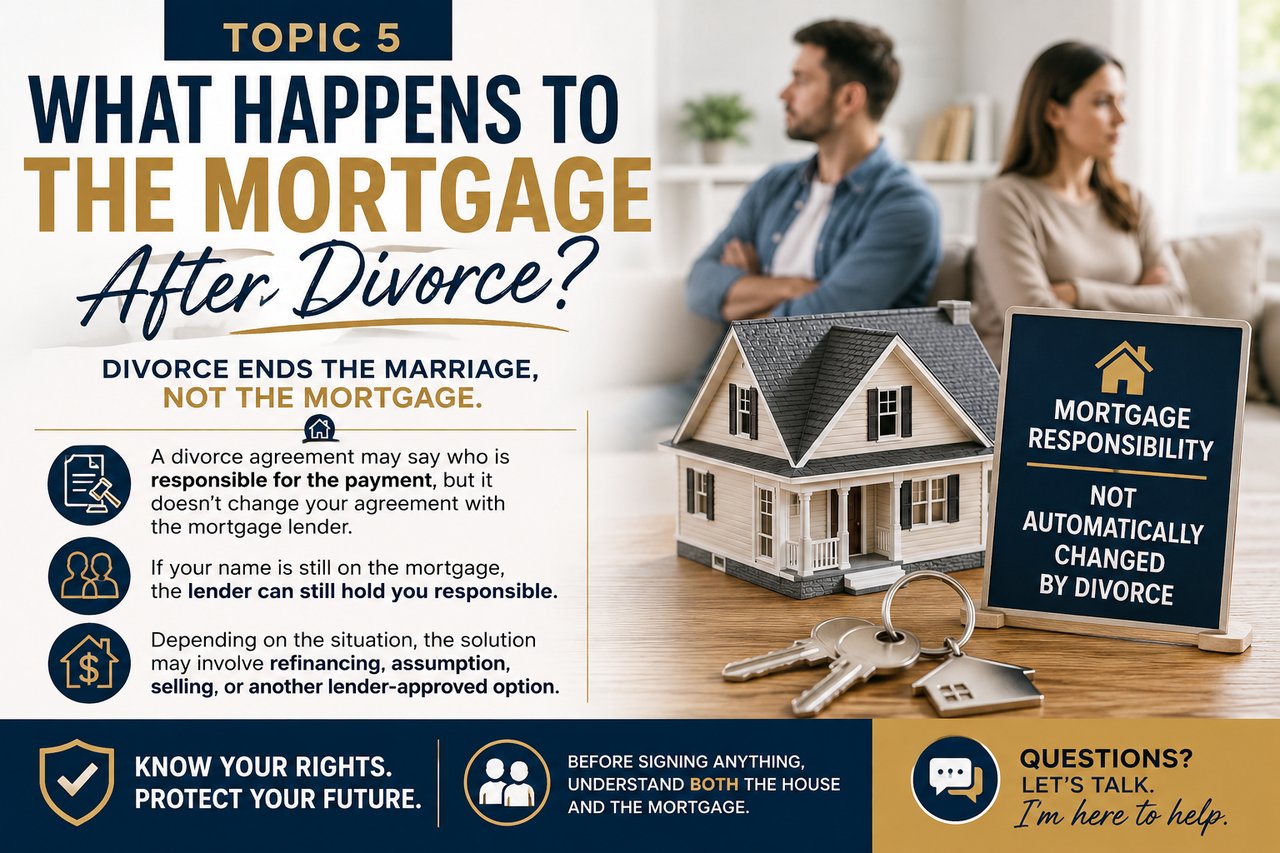
The existing mortgage also needs attention. If both spouses signed the loan, transferring the property to one spouse does not automatically release the departing spouse from mortgage liability. A deed transfer resolves ownership. It does nothing to the loan on its own. The departing spouse generally stays financially tied to that mortgage until it's refinanced, formally assumed with lender approval, or paid off entirely, regardless of what the settlement agreement says about who's "responsible" for it.
This is often the step that gets rushed or skipped, and it's the one most likely to come back and cause problems years later, showing up on a credit report or blocking a future mortgage application for the spouse who thought they were done with the house.
Why This Needs More Than a Real Estate Conversation
That is why a real-estate valuation should be just one part of a coordinated conversation involving the appropriate attorney, lender, financial advisor and tax professional. Here's how those roles typically break down:
- Your Realtor establishes what the property is actually worth in today's market.
- Your attorney applies Pennsylvania's equitable distribution factors to determine a fair division and structures the settlement language.
- Your lender confirms what the buying spouse can actually qualify for, and how the refinance or assumption will work mechanically.
- Your financial advisor helps weigh whether offsetting equity against other assets makes more sense than a cash buyout.
- Your tax professional flags any consequences tied to how the transfer and buyout are structured.
Skip any one of these, and the buyout that looked clean on paper can turn into a financing problem, a tax surprise, or a departing spouse who's still legally tied to a house they don't own six months later.
A Practical Checklist Before Finalizing a Buyout
- Get a current, professional market valuation rather than relying on an online estimate.
- Confirm with your attorney how Pennsylvania's equitable distribution factors apply to your specific circumstances.
- Talk to a lender early about refinance qualification, so the buyout number in the settlement is actually achievable.
- Decide with your financial advisor whether a cash buyout or an asset offset makes more sense for your overall financial picture.
- Get the mortgage resolution, refinance, assumption, or payoff, documented with a clear timeline in the settlement itself, not left as an informal understanding.
The Bottom Line
A divorce home buyout starts with an accurate value, but the value is only the opening number. What percentage of that equity gets paid out is a legal question under Pennsylvania's equitable distribution law, how the buyout gets funded is a financing question, and what happens to the existing mortgage is a separate liability question that doesn't resolve itself. Treating a buyout as a single real estate transaction, instead of a coordinated legal, financial, and lending decision, is where most of the costly mistakes happen.
FAQ: Divorce Home Buyouts
How is a divorce home buyout calculated? It generally starts with the property's market value minus the mortgage balance to establish gross equity. From there, how much of that equity actually gets paid to the departing spouse is determined under the state's property division law, in Pennsylvania that's equitable distribution rather than an automatic 50/50 split, along with any negotiated adjustments for closing costs, taxes, or other obligations.
Does a house buyout have to be 50/50 in Pennsylvania? No. Pennsylvania uses equitable distribution under 23 Pa.C.S. § 3502, which means the division of marital property, including home equity, is based on the specific circumstances of the marriage and a set of statutory factors, not an automatic even split.
How do most people fund a divorce house buyout? Common funding sources include available cash, offsetting the buyout against other marital assets like retirement accounts, or refinancing the mortgage to pull out enough equity to pay the departing spouse. Which option makes sense depends on qualification, liquidity, and the overall settlement structure.
If my spouse buys me out, does that remove me from the mortgage? Not automatically. If both spouses are on the original loan, transferring ownership to one spouse does not release the other from mortgage liability. That generally requires a refinance, a lender-approved assumption, or payoff of the loan.
Who should be involved in deciding a divorce home buyout? Ideally more than just a Realtor. A coordinated buyout typically involves a real estate professional for valuation, an attorney for the legal division, a lender for financing, a financial advisor for weighing asset tradeoffs, and a tax professional for any consequences tied to the transfer.
Related Reading
Best Selling Options in a Divorce (free guide)
Can You Buy Another House Before Your Divorce Is Final?
How Do You Determine What a House Is Worth During Divorce?
What Happens When One Spouse Wants to Sell the House and the Other Doesn't?
Does Taking Your Name Off the Deed Remove You From the Mortgage?
Should You Sell the House Before or After the Divorce Is Final?
What Happens to the Mortgage After Divorce?
Does Pennsylvania Split the House 50/50 in a Divorce?
Sources
- 23 Pa.C.S. § 3502, Equitable Division of Marital Property — https://www.legis.state.pa.us/WU01/LI/LI/CT/HTM/23/00.035.002.000..HTM
- DivorceNet, "House Buyout in Divorce: Buying Out Your Spouse's Share" — https://www.divorcenet.com/resources/divorce/marital-property-division/negotiating-a-house-buyout-div
- EffectiveAgents, "How Divorce Affects Your Mortgage: A Complete Buyout & Refinance Guide" — https://www.effectiveagents.com/resources/how-divorce-affects-your-mortgage-a-complete-buyout-refinance-guide
About the Author
Aubre Stacknick is a Global Real Estate Advisor with Piatt Sotheby's International Realty, serving Pittsburgh and the surrounding area. With 20+ years across construction, custom home building, and real estate, and having navigated divorce herself, she brings a practical, firsthand understanding of both the financial and emotional sides of buying, selling, or holding property through a divorce.
📞 412-721-3496 📧 [email protected] 🌐 www.aubrestacknick.com
Curious what your home is worth in today's market? Get a free home valuation and find out where you stand.
divorce home buyout, how does a house buyout work in divorce, divorce equity split, Pennsylvania equitable distribution buyout, refinance divorce buyout, divorce real estate Pittsburgh
This blog is for general informational purposes only and is not legal, financial, or tax advice. Confirm your specific situation with your attorney, lender, and tax professional.