Does Taking My Name Off the Deed Remove Me From the Mortgage?
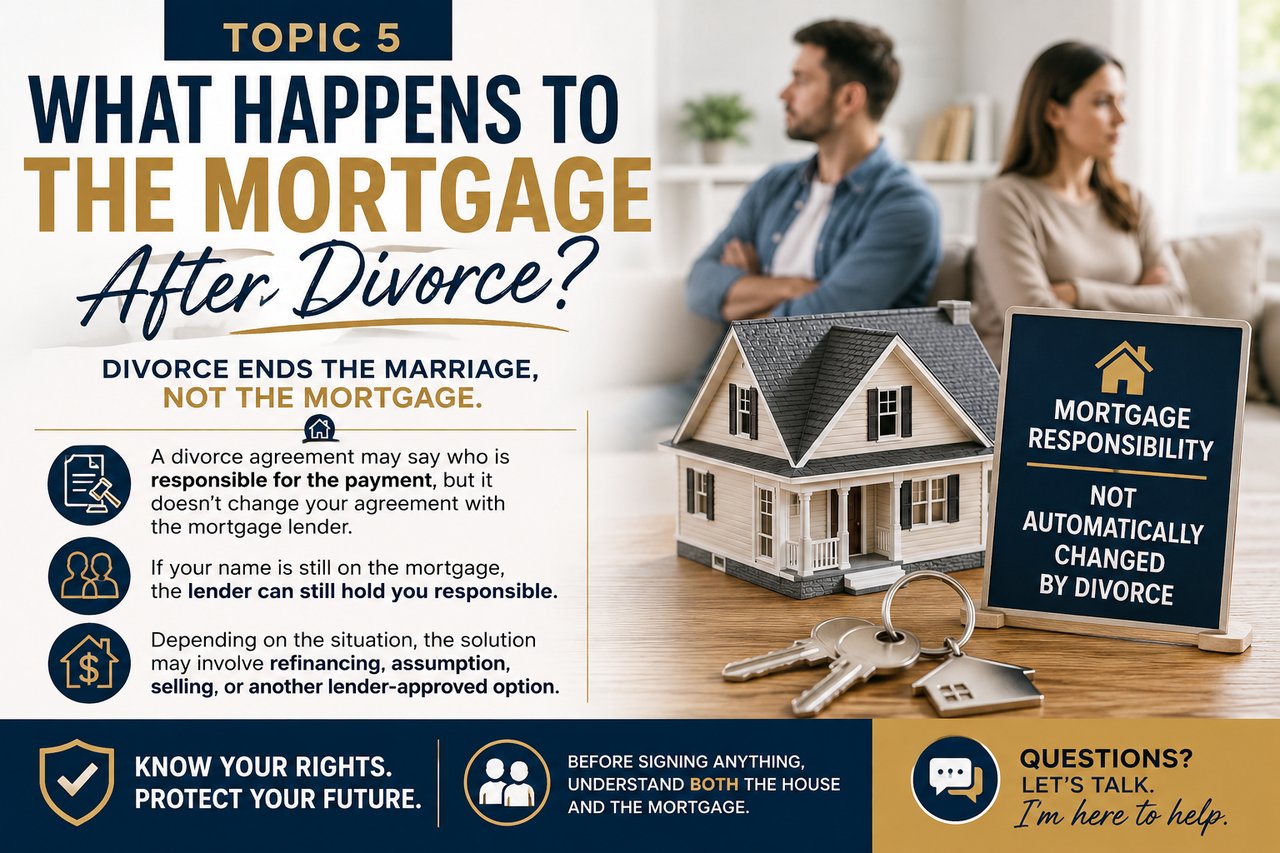
Generally, no. This is one of the most important, and most misunderstood, distinctions in divorce real estate, and getting it wrong can leave someone financially exposed on a house they no longer own.
Two Different Documents, Two Different Questions
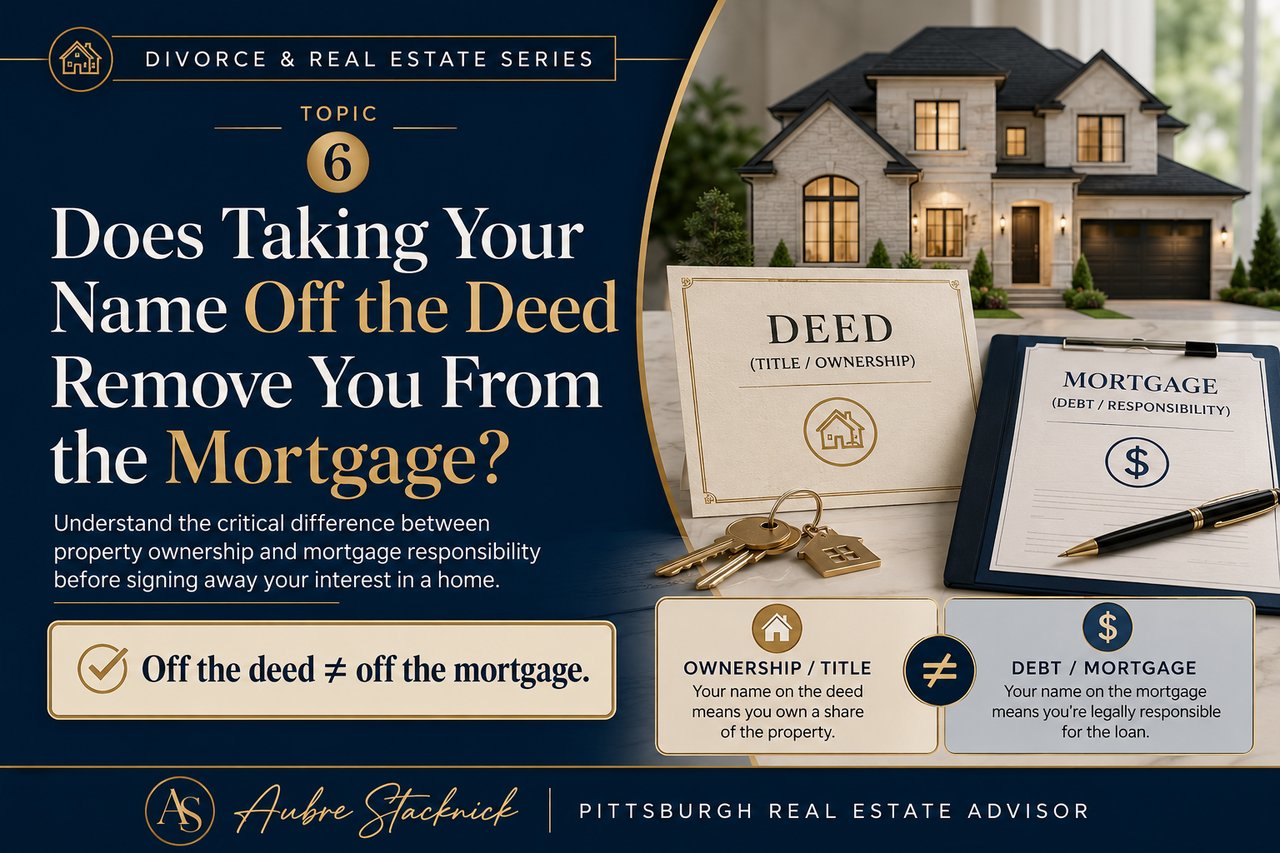
A deed concerns ownership of the real property. It answers the question: who owns this house?
A mortgage, or the promissory note behind it, concerns financial responsibility for borrowed money. It answers a completely different question: who owes the bank?
They were both signed at the same closing, years ago, but they don't move together after that. Transferring one does nothing to the other unless a separate step is taken to address it.
What the CFPB Says
The Consumer Financial Protection Bureau expressly warns that taking a person's name off a home's title does not automatically remove that person from the mortgage loan. That warning exists because this exact scenario trips up divorcing homeowners constantly. Someone signs a quitclaim deed, hands over their ownership interest, and assumes they're done. Then, months or years later, they try to buy their own place and their lender tells them they're still carrying the old mortgage on their credit report.
Imagine This Scenario
You transfer your ownership interest to your former spouse but remain contractually obligated for the mortgage. You may no longer own the house, but missed payments could potentially still create problems, because you remain a borrower. If your ex falls behind, here's what that can mean for you even though you don't own the home anymore:
- Late payments and collection activity can appear on your credit report.
- If the loan goes to foreclosure, your credit is affected right along with theirs.
- If the home sells for less than what's owed, the lender can potentially pursue you for the deficiency, since your name is still on the note.
- Your own ability to qualify for a new mortgage can be hurt by a debt tied to a house you don't even live in or own anymore.
This is why homeowners should understand the mortgage resolution before, or as part of, the ownership transfer, not treat the deed transfer as the finish line.
How the Mortgage Actually Gets Resolved
Depending on the circumstances, resolving your name on the loan might involve:
- Selling the property. The loan is paid off at closing, and both spouses' liability ends with the sale.
- Refinancing. The spouse keeping the home takes out a new loan in their name only, using it to pay off the old joint mortgage. This is the most common and cleanest solution, but the remaining spouse has to independently qualify based on their own income, credit, and debt-to-income ratio.
- An approved assumption and release. Certain loan types, particularly FHA and VA loans, may allow one spouse to formally assume the existing loan while the lender releases the other from liability. This route is less common on conventional loans and depends entirely on lender approval.
- Another solution authorized by the lender. Some lenders will consider a loan modification or other release of liability, though this is less common and entirely at the lender's discretion.
Notice the common thread: every one of these requires the lender's involvement. A deed transfer alone, and a divorce decree alone, don't accomplish any of them on their own. The bank was never a party to the divorce, and it isn't bound by what the decree says about who's "supposed" to be responsible.
Don't Treat the Deed as Proof the Mortgage Problem Is Resolved
This is the mistake that catches people off guard. A signed quitclaim deed feels like closure. It resolves ownership, and that part is real. But it says nothing about the loan. Confirm the mortgage resolution with the lender and your legal counsel directly, in writing, rather than assuming a real estate document settled a financial one.
A Few Practical Steps
- Before finalizing the divorce settlement, get clarity in writing on exactly how and when the mortgage will be refinanced, assumed, or paid off, not just who "gets" the house.
- If you're the spouse transferring away ownership, don't sign the quitclaim deed as your only protective step. Push for the refinance or release to happen alongside it, or as close to it as possible.
- If a full resolution can't happen immediately, document payment responsibility clearly in the settlement agreement, and monitor your credit report to catch problems early rather than after they've compounded.
- Talk to a lender early about what refinancing or assumption would actually require, so the settlement terms are realistic rather than aspirational.
The Bottom Line
A deed and a mortgage are two separate legal instruments that answer two separate questions. Transferring ownership does not, by itself, transfer financial responsibility for the loan. If your name is on the mortgage, it stays there until the lender says otherwise, regardless of what the deed or even the divorce decree says. Confirm the mortgage resolution with your lender and your attorney before you consider this part of the divorce settled.
FAQ: Deed vs. Mortgage in Divorce
Does signing a quitclaim deed remove my name from the mortgage? No. A quitclaim deed transfers your ownership interest in the property, but it has no effect on the mortgage loan. You remain legally responsible for the debt until the lender formally releases you, typically through a refinance, an approved assumption, or payoff of the loan.
What happens if my ex stops paying the mortgage after I sign a quitclaim deed? If your name is still on the loan, missed payments and any resulting foreclosure can still affect your credit, even though you no longer own the property. The lender can also pursue you for any deficiency if the home is later sold or foreclosed for less than what's owed.
How do I get my name off the mortgage after divorce? The most common way is refinancing, where the spouse keeping the home takes out a new loan solely in their name and pays off the old joint mortgage. Depending on the loan type, an approved assumption and release, or another lender-approved solution, may also be possible.
Does the divorce decree remove me from the mortgage automatically? No. A divorce decree is an agreement between spouses, but the lender was never a party to it and isn't bound by its terms. Only the lender can release a borrower from mortgage liability, typically through refinancing, an assumption and release, or payoff of the loan.
Should I sign a quitclaim deed before the mortgage is resolved? Not without understanding the risk. Signing away ownership while remaining on the loan can leave you financially exposed to a property you no longer control. It's generally best to have the mortgage resolution, such as a refinance timeline, addressed in writing as part of the settlement before or alongside the deed transfer.
Related Reading
Best Selling Options in a Divorce (free guide)
Can You Buy Another House Before Your Divorce Is Final?
How Do You Determine What a House Is Worth During Divorce?
What Happens When One Spouse Wants to Sell the House and the Other Doesn't?
Should You Sell the House Before or After the Divorce Is Final?
Sources
- Consumer Financial Protection Bureau, Ask CFPB — https://www.consumerfinance.gov/ask-cfpb/
- DeedClaim, "Removing a Spouse from a Mortgage After Divorce" — https://www.deedclaim.com/remove-spouse-mortgage-divorce/
- Florida Realtors, "Can a Quitclaim Deed Remove Someone From a Mortgage?" — https://www.floridarealtors.org/news-media/news-articles/2026/06/can-quitclaim-deed-remove-someone-mortgage
- PNC Insights, "Refinancing After a Divorce: What You Need to Know" — https://www.pnc.com/insights/personal-finance/borrow/refinancing-your-mortgage-after-a-divorce.html
About the Author
Aubre Stacknick is a Global Real Estate Advisor with Piatt Sotheby's International Realty, serving Pittsburgh and the surrounding area. With 20+ years across construction, custom home building, and real estate, and having navigated divorce herself, she brings a practical, firsthand understanding of both the financial and emotional sides of buying, selling, or holding property through a divorce.
📞 412-721-3496 📧 [email protected] 🌐 www.aubrestacknick.com
Curious what your home is worth in today's market? Get a free home valuation and find out where you stand.
deed vs mortgage divorce, quitclaim deed divorce, remove name from mortgage after divorce, CFPB divorce mortgage, mortgage refinance divorce, divorce real estate Pittsburgh
This blog is for general informational purposes only and is not legal or financial advice. Confirm your specific situation with your lender and attorney.