Divorce and the Marital Home: A Real Estate Framework Before You Decide Anything
For many couples, the marital home is one of their largest assets, and often the most emotional. That combination, a huge financial decision wrapped in a deeply personal one, is exactly why so many people make this decision backwards.
The First Question Isn't "Who Gets the House?"
But the first question shouldn't necessarily be "Who gets the house?" It should be: what is the house worth, what is owed against it, and what are the realistic options?
Starting with "who gets it" turns the house into a prize to be won or a fight to be avoided. Starting with the facts, value, debt, and real options, turns it into what it actually is: a financial asset that needs to be understood before it can be fairly divided.
Pennsylvania's Property Division Framework
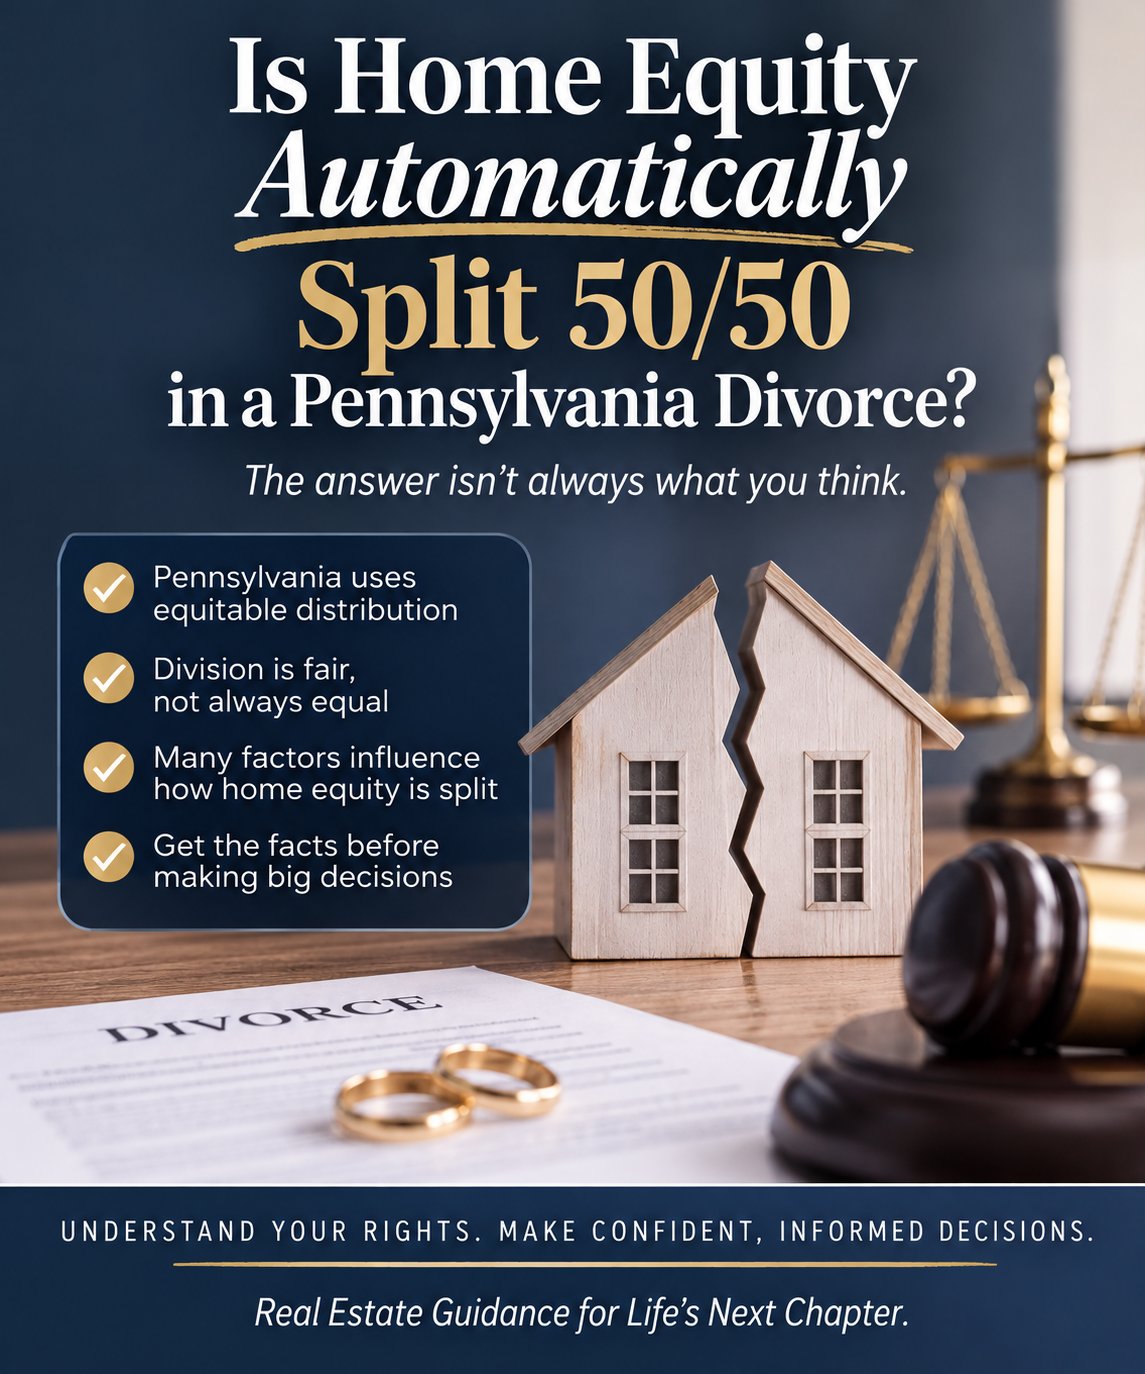
Pennsylvania follows equitable distribution rules for marital property. That does not automatically mean every marital asset is divided exactly 50/50. Pennsylvania law directs courts to consider numerous factors when determining an equitable division of marital property, factors that include the length of the marriage, each spouse's income, health, and earning capacity, contributions to the household, and the standard of living established during the marriage, among others, under 23 Pa.C.S. § 3502. That statute governs the legal side of the equation. This guide focuses on the real estate side: the facts you need before that legal conversation can even happen productively.
From a Real Estate Perspective, Three Outcomes Are Generally Possible
Sell the home. Selling can turn the property into cash and eliminate the existing real-estate relationship between the spouses after closing. This is often the cleanest option, since it converts an illiquid, shared asset into a defined amount of money that can be divided, and it ends both spouses' financial connection to the property once the loan is paid off at closing.
One spouse keeps it. That may involve addressing the other spouse's interest in the property and determining what happens to the existing mortgage. This is rarely as simple as changing whose name is on the deed. It usually requires a buyout, whether in cash, through an asset offset, or through a refinance, and it requires a separate resolution of the mortgage itself, since a deed transfer alone doesn't remove either spouse's liability on the loan.
Continue owning it temporarily. Sometimes couples postpone selling because of children, market conditions, or other circumstances. This can make sense, particularly to preserve stability for kids mid-school-year or to avoid selling into a soft market, but it should come with a clear plan and timeline, not an open-ended arrangement that leaves both spouses financially tied to the property indefinitely.
Whatever Option Is Being Considered, Start With Reliable Information
Before deciding between these three paths, gather the actual numbers:
- Determine the property's probable market value. Not an app estimate, a real, current, professional read on what the home would likely sell for today.
- Find the current mortgage balance and any other liens. This includes the primary mortgage, any home equity loans or lines of credit, and any other recorded liens against the property.
- Estimate the equity. Market value minus what's owed gives you gross equity, the starting figure for any buyout, offset, or sale-proceeds conversation.
- Understand selling expenses. If a sale is on the table, total seller costs, commissions, closing costs, repairs, and related fees, commonly run in the range of 6% to 10% of the sale price nationally, sometimes higher depending on the market and how the transaction is structured. On a $600,000 home, that's a real range of roughly $36,000 to $60,000 coming off the top before anyone sees a check.
- Calculate what it actually costs to maintain the property. Beyond the mortgage, factor in property taxes, insurance, HOA fees if applicable, utilities, and a realistic maintenance reserve, commonly estimated at roughly 1% to 4% of the home's value per year depending on its age and condition.
Every one of these numbers changes the conversation. A house with thin equity and high carrying costs is a very different decision than one with substantial equity and a mortgage payment well within a single income.
Title and Mortgage Liability Are Not the Same Thing
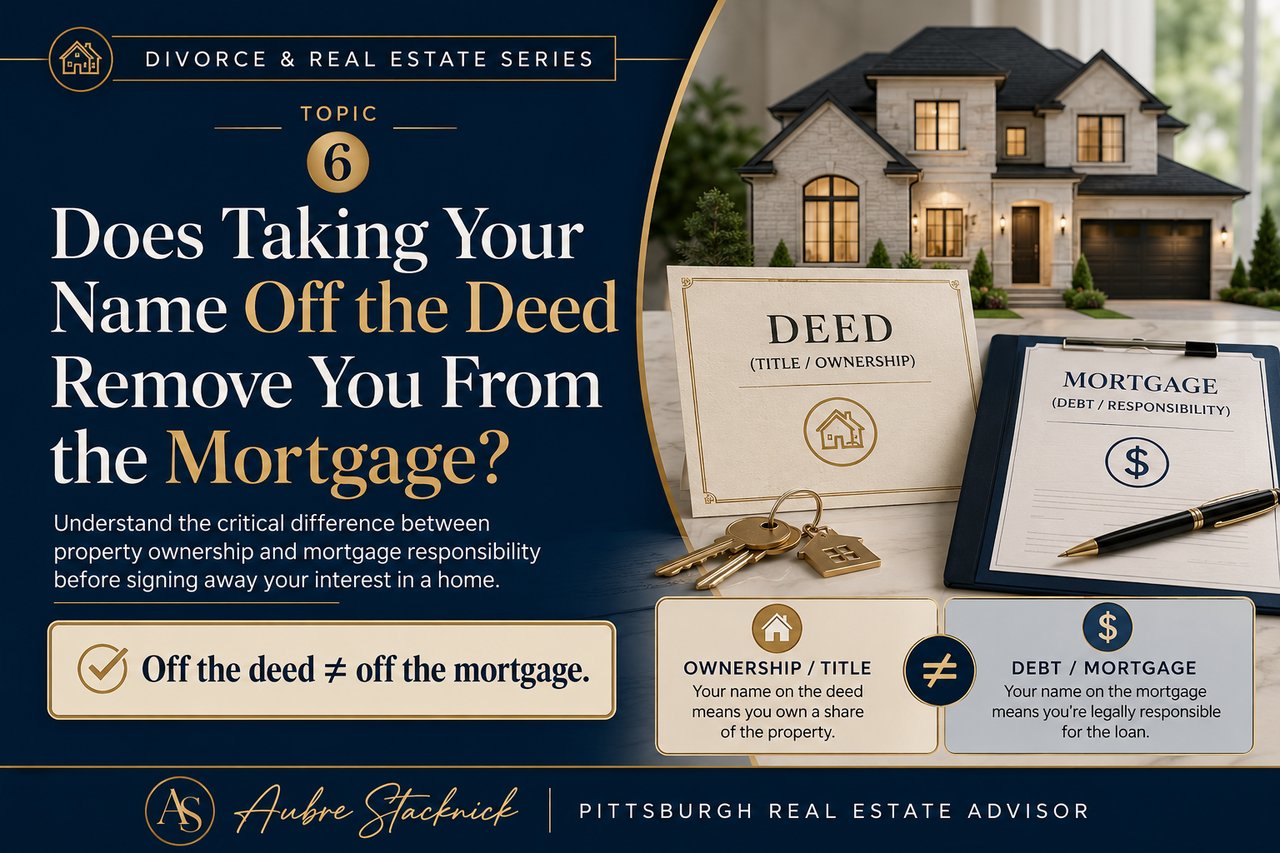
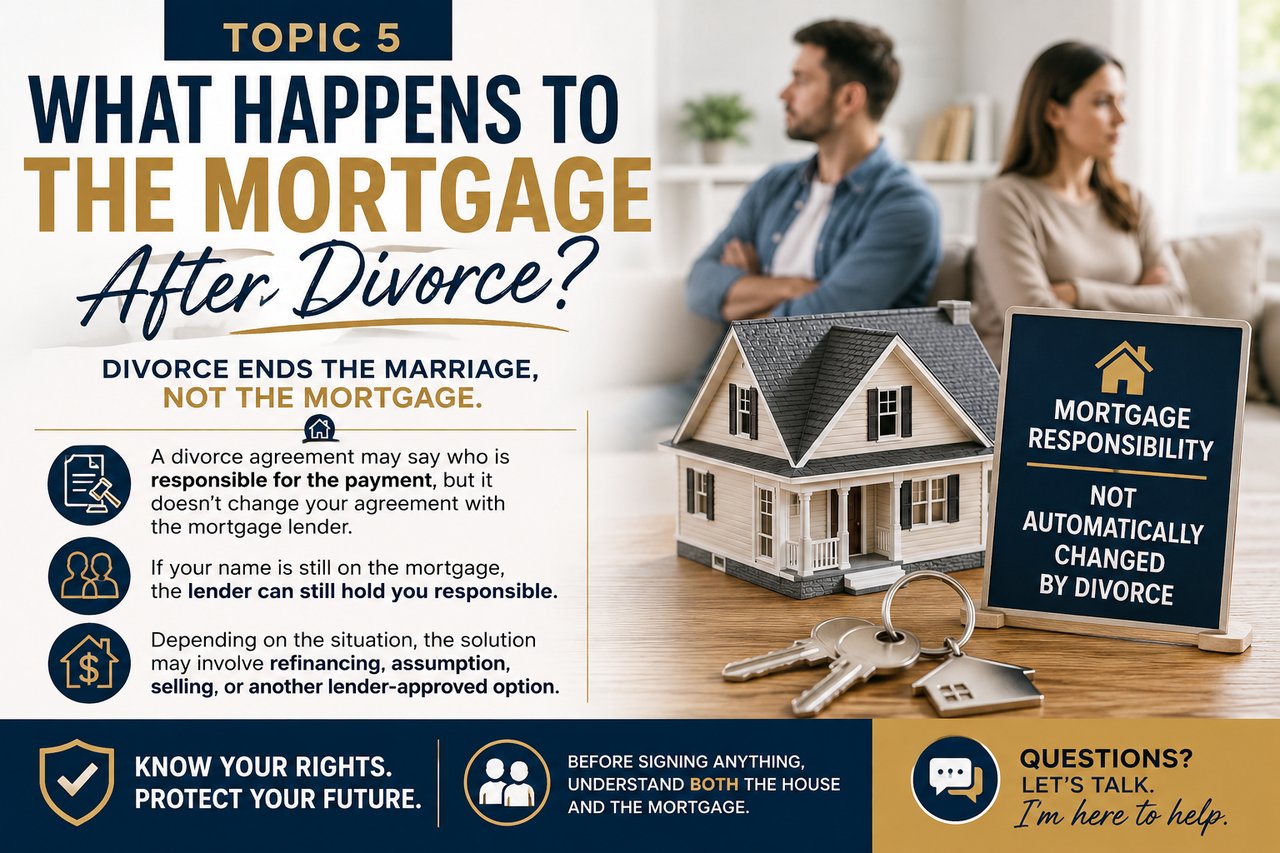
There is also an important distinction between title and mortgage liability. A divorce decree or property agreement can allocate responsibility between spouses, but it does not automatically change a lender's rights against someone who remains contractually obligated on a mortgage.
This trips up more divorcing homeowners than almost anything else in this process. The deed answers who owns the house. The mortgage answers who owes the bank. They're separate documents, and resolving one does nothing to resolve the other. If both spouses signed the original loan, both generally remain liable to the lender until the loan is refinanced, formally assumed with the lender's approval, or paid off, regardless of what the settlement says about who's "responsible" for it. Federal consumer protection guidance specifically recognizes this gap and has addressed both the risks it creates and, in some cases, options like loan assumption for a spouse who receives the property through divorce, subject to the lender's underwriting requirements.
The Goal Isn't a Predetermined Answer
The goal should not automatically be to keep the home or automatically sell it. The goal is to understand what each option means financially and practically before making the decision.
That's a harder standard than it sounds like, because divorce creates real pressure to decide quickly, to keep the house for the kids, to sell it and be done, to avoid dealing with an ex-spouse any longer than necessary. None of those instincts are wrong, but none of them should substitute for actually knowing the numbers first.
A Practical Starting Checklist
- Get a current, professional market valuation of the property.
- Pull the current mortgage balance and confirm any additional liens.
- Calculate gross equity and understand how it fits into your state's property division framework.
- Get a realistic estimate of selling costs if a sale is on the table.
- Calculate the full cost of keeping the home, not just the mortgage, if that's being considered.
- Confirm with a lender what refinancing or an assumption would actually require.
- Bring all of this to your family-law attorney, who can apply it to your specific legal situation.
The Bottom Line
The marital home is too large a decision to make on instinct alone, and too complicated to make on legal advice alone, or on real estate advice alone. Selling, keeping, or temporarily continuing ownership are all legitimate paths, but each one only makes sense once you actually know the property's value, what's owed against it, what it costs to maintain, and how title and mortgage liability actually work. Get the facts first. Let the decision follow from there.
Knowledge Starts with Knowing®.
FAQ: Divorce and the Marital Home
What's the first step when deciding what to do with the house in a divorce? Start with the facts rather than a decision: the property's current market value, the mortgage balance and any liens, the resulting equity, and what it would cost to sell versus continue owning it. Those numbers should inform the decision between selling, one spouse keeping the home, or temporary continued ownership.
Does Pennsylvania automatically split home equity 50/50 in a divorce? No. Pennsylvania uses equitable distribution under 23 Pa.C.S. § 3502, meaning courts divide marital property based on statutory factors specific to the marriage, not an automatic even split.
What are the three main options for the marital home in a divorce? Generally: selling the home and dividing the proceeds, one spouse keeping the home and addressing the other's equity interest and the mortgage, or temporarily continuing joint ownership, often due to children, market conditions, or other circumstances, with a clear plan for resolving it later.
How much does it typically cost to sell a house? Total seller costs, including agent commissions, closing costs, and repairs, commonly range from about 6% to 10% of the sale price nationally, though this varies by market and how the transaction is structured.
Does a divorce decree change who is responsible for the mortgage with the lender? Not on its own. A divorce decree is an agreement between spouses, but the mortgage lender was never a party to it. If both spouses are on the original loan, both generally remain liable to the lender until the loan is refinanced, assumed with approval, or paid off, regardless of what the decree says.
Related Reading
Best Selling Options in a Divorce (free guide)
Can You Buy Another House Before Your Divorce Is Final?
How Do You Determine What a House Is Worth During Divorce?
What Happens When One Spouse Wants to Sell the House and the Other Doesn't?
Does Taking Your Name Off the Deed Remove You From the Mortgage?
Should You Sell the House Before or After the Divorce Is Final?
What Happens to the Mortgage After Divorce?
Does Pennsylvania Split the House 50/50 in a Divorce?
How Does Buying Your Spouse Out of the House Work?
Can One Spouse Keep the House After Divorce?
Sources
- 23 Pa.C.S. § 3502, Equitable Division of Marital Property — https://www.legis.state.pa.us/WU01/LI/LI/CT/HTM/23/00.035.002.000..HTM
- Consumer Financial Protection Bureau, "Issue Spotlight: Homeowners face problems with mortgage companies after divorce or death of a loved one" — https://www.consumerfinance.gov/data-research/research-reports/homeowners-face-problems-with-mortgage-companies-after-divorce-or-death-of-a-loved-one/
- Homes.com, "How much does it cost to sell a home?" — https://www.homes.com/learn/how-much-does-it-cost-to-sell-a-home/
- State Farm, "How Much To Budget for Home Maintenance" — https://www.statefarm.com/simple-insights/residence/how-to-budget-and-save-for-home-maintenance
About the Author
Aubre Stacknick is a Global Real Estate Advisor with Piatt Sotheby's International Realty, serving Pittsburgh and the surrounding area. With 20+ years across construction, custom home building, and real estate, and having navigated divorce herself, she brings a practical, firsthand understanding of both the financial and emotional sides of buying, selling, or holding property through a divorce.
📞 412-721-3496 📧 [email protected] 🌐 www.aubrestacknick.com
Curious what your home is worth in today's market? Get a free home valuation and find out where you stand.
divorce and the marital home, house in a divorce Pennsylvania, sell or keep the house divorce, divorce real estate framework, equitable distribution home, divorce real estate Pittsburgh
General real-estate information only. Consult your Pennsylvania family-law attorney, lender, CPA and financial advisor regarding your individual circumstances.